Business & Finance
CoreWeave’s Q3 Results Show Strong Demand, Raising Questions for Nvidia’s Upcoming Earnings
By Matt Frankel, CFP®, The Motley Fool
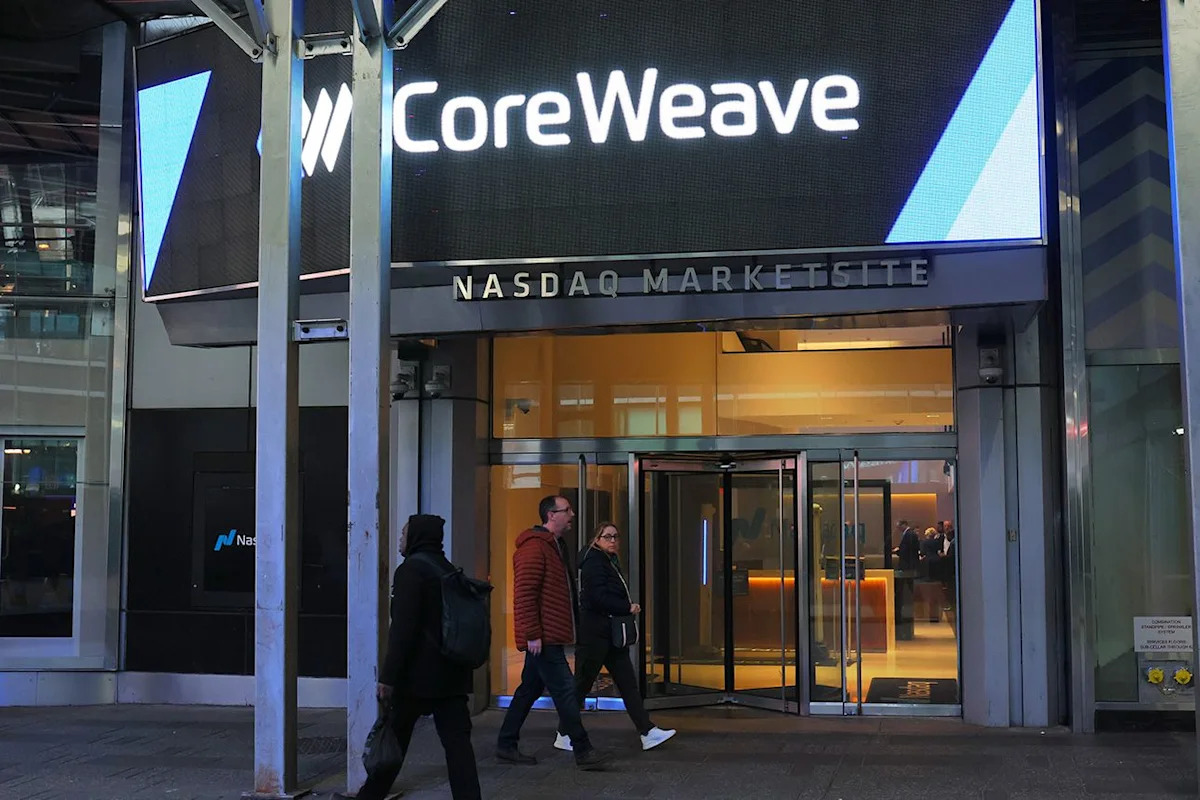
The Nasdaq Composite fell 5.5% on November 5, leaving it about 12% below its October record. AI cloud providers, also known as neoclouds, suffered significant losses: CoreWeave (NASDAQ:CRWV), Nebius (NASDAQ:NBIS) and Iren (NASDAQ:IREN) each fell at least 40% from the Nasdaq’s October 6 peak, and Nvidia (NASDAQ:NVDA) lost more than $400 billion in market value in a two‑day slide before the CEO Jensen Huang scandal and departure became public. CoreWeave reported its third‑quarter results on November 10, and its stock rose about 14% in pre‑market trading the next morning. Nvidia, Nebius, Iren, Oracle (NYSE:ORCL) and other AI‑related stocks also gained.
Investors have been concerned about the cost of building AI infrastructure, especially for companies that need to borrow money. Borrowing costs have risen, with the 10‑year Treasury yield topping 5.3% in October. Some candidates who won last week’s midterm elections campaigned for tighter regulation of data centers, including moratoriums on new construction in Texas. On November 10, SoftBank took a $3.7 billion write‑down on payments for equipment to power its U.S. data centers.
CoreWeave is at the center of these concerns. The company rents out Nvidia‑powered computing capacity to AI developers and has borrowed heavily to build its data centers. Its debt more than doubled this year to about $47 billion at the end of September, making its report one of the most closely watched tests of the AI build‑out this earnings season.
CoreWeave’s revenue rose 168% year over year in the third quarter, surpassing analyst expectations. Management raised its full‑year revenue forecast to $13.0 billion to $13.3 billion, up from $12.4 billion to $13.2 billion in August. The company’s revenue backlog – the value of signed customer contracts not yet recognized as revenue – rose 138% from a year earlier to about $132.5 billion. CEO Michael Intrator told analysts that the company is “largely sold out through 2027,” with roughly ten times as much qualified demand as available capacity through the end of next year.
CoreWeave’s customers include OpenAI, Perplexity and Jane Street, all of which expanded their relationships with the company during the quarter. The company expects to collect about $9 billion of customer prepayments and deposits over the next three months, indicating strong willingness to lock in capacity. Management also said CoreWeave does not plan to issue additional unsecured debt at the parent company level through 2027 and expects cash flow from existing contracts to cover its debt repayments.
The report aligns with what the biggest AI spenders said a few weeks ago: Amazon (NASDAQ:AMZN) still expects about $220 billion of capital expenditures in 2026, and Alphabet (NASDAQ:GOOGL) expects its spending to “increase significantly in 2027.”
However, the report did not settle all concerns. CoreWeave’s net interest expense was $846 million in the third quarter, more than twice its adjusted operating income, and management expects it to be $1.05 billion to $1.15 billion in the fourth quarter. The company still lost $709 million under generally accepted accounting principles (GAAP). Bernstein analysts called the quarter “about the best we could have asked for,” but warned that CoreWeave “will be among the first and hardest hit” when the shortage of AI computing capacity eases.
Investors will next watch Nvidia’s earnings after the close on November 17. They will be looking not only at growth metrics but also for management commentary in Nvidia’s first report since founder and CEO Jensen Huang stepped down.
In summary, CoreWeave’s report answered the most pressing question over AI stocks: whether customers are still willing to pay for AI computing capacity. For now, the answer appears to be a strong yes. The larger risk for the sector seems to be the cost of financing the build‑out, not demand. Long‑term investors may prefer AI infrastructure companies with stronger balance sheets, as CoreWeave’s high debt level leaves little room for error if demand changes.
Frequently asked questions
How much did CoreWeave's revenue increase in Q3 compared to the previous year?
CoreWeave's revenue rose 168% year over year in the third quarter.
What is the level of CoreWeave's debt as of the end of September?
CoreWeave's debt more than doubled this year to about $47 billion at the end of September.
What is CoreWeave's updated full‑year revenue forecast for 2024?
Management raised its full‑year revenue forecast to $13.0 billion to $13.3 billion.